
Real Estate: How a Cost Segregation Study Can Benefit You
When you buy an income-producing property, part of the investment is recovered through depreciation deductions. A cost segregation study can move some of those deductions into earlier years, potentially reducing current taxable income and leaving more cash available for your next investment.
Whether that produces a meaningful benefit depends on the property, your ability to use the deductions and how long you expect to hold the investment.
What is a cost segregation study
A cost segregation study identifies and assigns costs to the different components of a property for tax depreciation purposes. Instead of treating every depreciable dollar as part of the building, the study separates qualifying personal property and land improvements into appropriate asset classes. [1]
Under the general federal depreciation system, residential rental buildings are typically depreciated over 27.5 years and commercial buildings over 39 years. Certain components may qualify for 5-, 7- or 15-year recovery periods. Depending on the facts, examples can include appliances, carpeting, qualifying equipment, and certain parking or landscaping improvements. Structural components and systems serving the building generally remain with the building. Land itself is not depreciable. [1, 2, 3]
Classification depends on the component's function and the applicable tax rules. A defensible study explains those classifications and reconciles its allocations to the property's tax basis. [1]
How it can lower taxable income
Depreciation reduces taxable profit even though taking the deduction does not require a new cash payment that year. By identifying assets with shorter recovery periods, cost segregation can accelerate the deductions associated with a property you already purchased or improved.
Bonus depreciation may increase the upfront deduction further. Current law generally allows 100% bonus depreciation for qualifying property acquired and placed in service after January 19, 2025, subject to eligibility rules. Qualifying shorter-lived components identified in a study may be eligible, while the building and land generally are not. [4]
The resulting deduction can reduce rental or business income. If it creates a loss, separate tax rules determine whether you can use that loss against other income immediately.
A simplified example
Assume an investor buys a residential rental property in 2026 for $1 million. A supported allocation assigns $200,000 to land and $800,000 to depreciable property. A study identifies $200,000 of eligible shorter-lived components, leaving $600,000 assigned to the building.
The property is placed in service in July. Using the residential building's mid-month convention, the first year includes 5.5 months of building depreciation. If the identified components qualify for 100% bonus depreciation, the comparison is:
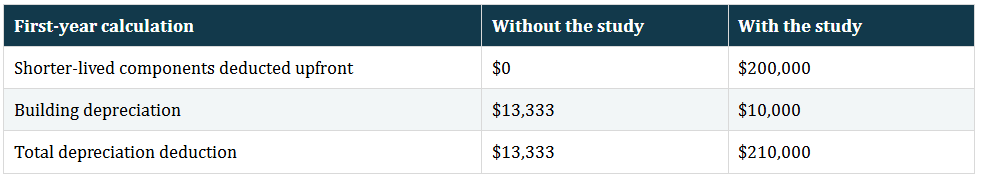
The additional first-year deduction is approximately $196,667. If the entire difference reduces income otherwise taxed at a 32% federal rate, the illustrative current federal tax reduction is about $62,933 before study fees and state taxes. [2, 4]
This is a hypothetical calculation, not an expected allocation or a guaranteed result. It assumes an eligible acquisition, full rental use, no election that disqualifies the assets from bonus depreciation, and full current use of the deductions. It also ignores interactions with the QBI deduction and other tax provisions. A deduction reduces taxable income; it is not a dollar-for-dollar tax credit.
Who can benefit
Cost segregation may be useful for owners of apartment buildings, commercial properties, warehouses and other rental or business real estate. It can also be worth evaluating for a single rental property or a substantial renovation when the expected benefit justifies the study's cost.
Owners with taxable rental income or income from an operating business using the property may have a clear opportunity to use accelerated deductions. Investors with passive income from other activities may also benefit, subject to the rules governing those activities. [5]
The analysis should consider the property's component mix, your income, the expected holding period and the cost of obtaining and implementing the study. There is no single purchase-price threshold that makes a study worthwhile for every owner.
Why a large deduction may not create immediate savings
Rental losses are generally passive and ordinarily cannot offset wages or other nonpassive income. Disallowed losses may be carried forward. Exceptions can apply, including rules for qualifying real estate professionals who also materially participate in the relevant rental activities. Short-term rentals have separate activity and participation rules; owning a vacation rental alone does not establish eligibility. [5]
Entity basis limits, at-risk rules and other loss limitations may also restrict deductions. A property held through a partnership or S corporation requires analysis at both the entity and owner levels. [5]
Real estate businesses that elect out of Section 163(j) generally must use the alternative depreciation system for their buildings and qualified improvement property. That can affect bonus depreciation eligibility for those assets, but it does not automatically disqualify every shorter-lived asset identified in a study. [6]
Can a study help with a property you already own
Often, yes. A study may identify depreciation that should have been taken in earlier years. Depending on the circumstances, an accounting method change using Form 3115 and a Section 481(a) adjustment can allow a catch-up deduction. The proper procedure depends on the filing history and applicable rules. [3, 7]
A study performed today does not automatically apply today's bonus depreciation percentage to an older acquisition. The property's original acquisition and placed-in-service dates remain relevant.
Consider the eventual sale
Cost segregation generally changes the timing of deductions. Accelerating depreciation leaves less basis to deduct later and may increase depreciation recapture when the property is sold. Gain attributable to certain personal property can be taxed as ordinary income. [8]
That makes the planned holding period important. We evaluate the potential current benefit alongside the likely sale consequences, rather than judging a study solely by its first-year deduction.
Start with the property and your tax position
Before commissioning a study, gather the purchase closing statement, existing depreciation schedules, renovation invoices and construction records. A qualified study provider should support the classifications and cost allocations with appropriate documentation. [1]
At Nathrop Maxwell Advisors, we help real estate owners assess the tax benefit of cost segregation and how it fits into their broader plans. Contact us to review your property and determine whether a study is worth pursuing.
This article provides general federal tax information as of October, 2026. The example is illustrative, and actual deductions and savings depend on your circumstances.
Sources
1. IRS Cost Segregation Audit Techniques Guide — background on study methods and documentation; not a binding statement of law
2. IRS Publication 527 on rental property
3. IRS Publication 946 on depreciation
4. IRS bonus depreciation guidance
5. IRS Publication 925 on passive activity and at-risk rules
6. IRS business interest limitation questions and answers
8. IRS Publication 544 on asset dispositions and depreciation recapture